Most homeowners policies cover sudden and accidental water damage and fire and smoke damage. Your job is to stop the damage from getting worse and document it. Our job is to do the mitigation, record everything adjusters need and keep the claim moving.
What we do on every insurance job
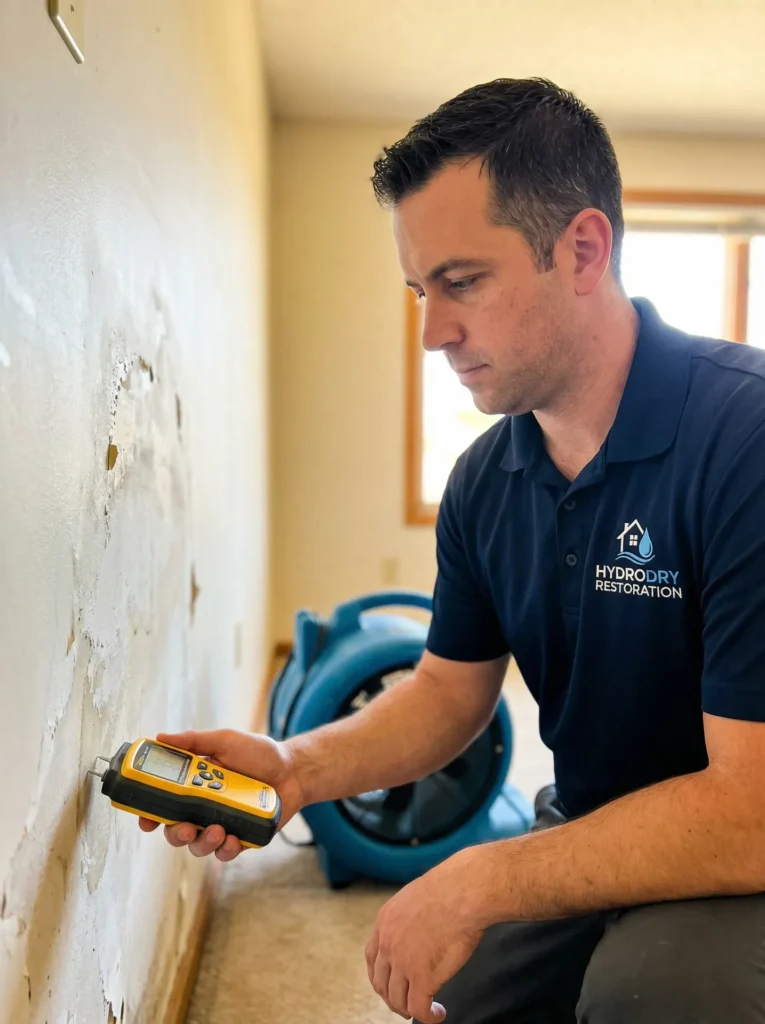
- Photos before we touch anything. Every affected room, the source and the damage.
- Moisture mapping and daily drying logs. Readings that prove the loss and show when it is dry.
- A scope in adjuster format. Line items priced the way carriers review them.
- Adjuster communication. We meet your adjuster on-site or by video and answer their questions.
- Direct billing. On covered claims, we can bill the carrier directly, so you usually pay only your deductible.
What is usually covered, and what usually is not
| Usually covered | Often excluded or limited |
|---|---|
| Burst or frozen pipes in a heated home | Long-term slow leaks and seepage |
| Water heater, washer or appliance failure | Surface or rising flood water (needs flood insurance) |
| Fire, smoke and soot damage | Sewer or drain backup without a backup endorsement |
| Water from firefighting | Mold from ongoing humidity or neglected leaks |
| Roof leaks from storm or ice dam damage | Wear and tear, old roofs, maintenance issues |
| Additional living expenses if you must move out | Freeze damage in a vacant or unheated home |
Every policy is different; your declarations page and policy wording decide. We are happy to look at it with you.
What to do in the first hour
- Stop the source if it is safe: water main, appliance valve or breaker.
- Take photos and video of everything before cleanup starts.
- Call HydroDry to begin mitigation and open a claim with your insurer.
- Keep receipts for anything you buy and any hotel stays.
- Do not throw away damaged items until the adjuster has seen them or we have documented them.
Start your claim the right way. Call us first.
Call 603-606-9171 24/7Frequently asked questions
Should I call my insurance company or a restoration company first?
Do both, but do not wait on the insurer to start mitigation. Your policy requires you to prevent further damage, and the adjuster may not arrive for days. Call us to stop the damage and call your insurer to open a claim. We document everything from the start.
Do I have to use the restoration company my insurer recommends?
No. In New Hampshire and Massachusetts you can choose your own contractor. Your insurer may suggest a preferred vendor, but the choice is yours.
Will filing a claim raise my rates?
It can, depending on your carrier and claim history. For small losses we will tell you honestly whether the repair cost is likely to exceed your deductible, so you can decide whether a claim makes sense.
What if my claim is denied?
We can provide our documentation, moisture logs and cause-of-loss notes to support an appeal, and we will tell you plainly if the damage falls under a common exclusion.
How long does an insurance claim take?
Mitigation starts right away. Adjuster inspection often happens within a few days to two weeks. Repair approval follows the adjuster's review of our scope and documentation.